Federal retirement income in 2027 comes from four moving parts: your FERS pension, your TSP savings, Social Security, and FEHB health coverage. The choices you make about each one affect what the others pay out.
Understanding how FERS, TSP, Social Security, and FEHB fit together is an important planning step for any federal employee in the year before retirement. The 2027 figures have shifted meaningfully from 2026. (Updated October 2026.)
This guide from Federal Pension Advisors, a retirement planning firm specializing in federal employee benefits, walks through each pillar as it stands for the 2027 plan year. You'll see confirmed figures from OPM, the U.S. Office of Personnel Management; the SSA, or Social Security Administration; and the IRS. Projected figures appear where official 2027 numbers aren't yet released. For a closer look at health insurance choices, review the 2027 FEHB enrollment tiers to understand the available enrollment options and coverage levels.
Acronyms used throughout: FERS (Federal Employees Retirement System), TSP (Thrift Savings Plan), OPM, SSA, and FEHB (Federal Employees Health Benefits Program).
How FERS, TSP, Social Security and FEHB Fit Together
FERS, TSP, Social Security, and FEHB fit together as four coordinated pillars of federal retirement. FERS pays a defined-benefit annuity for life, and the TSP pays out your personal savings and any agency match. However, events such as a Reduction in Force (RIF), Voluntary Early Retirement Authority (VERA), or Voluntary Separation Incentive Payment (VSIP) can affect how you approach these benefits. Understanding how federal workforce changes affect your retirement strategy can help you evaluate your options and prepare for potential changes.
Social Security pays a federally administered retirement benefit. FEHB continues your health coverage into retirement for those who meet OPM's five-year enrollment rule.
Its own agency governs each pillar, under its own rules. The choices you make, such as when to retire, when to claim Social Security, and which FEHB plan to carry into retirement, affect your overall retirement cash flow and coverage.
FERS replaced CSRS, the Civil Service Retirement System, for most federal employees entering service after 1983, with transitional coverage rules applying before FERS took effect in 1987. CSRS now serves a shrinking group of older federal retirees.
FERS pays a smaller base pension than CSRS, so the TSP and Social Security carry more weight in a FERS retirement income plan.
CSRS retirees often rely primarily on their CSRS annuity. Many also hold TSP savings and may qualify for Social Security benefits they earned through non-federal employment.
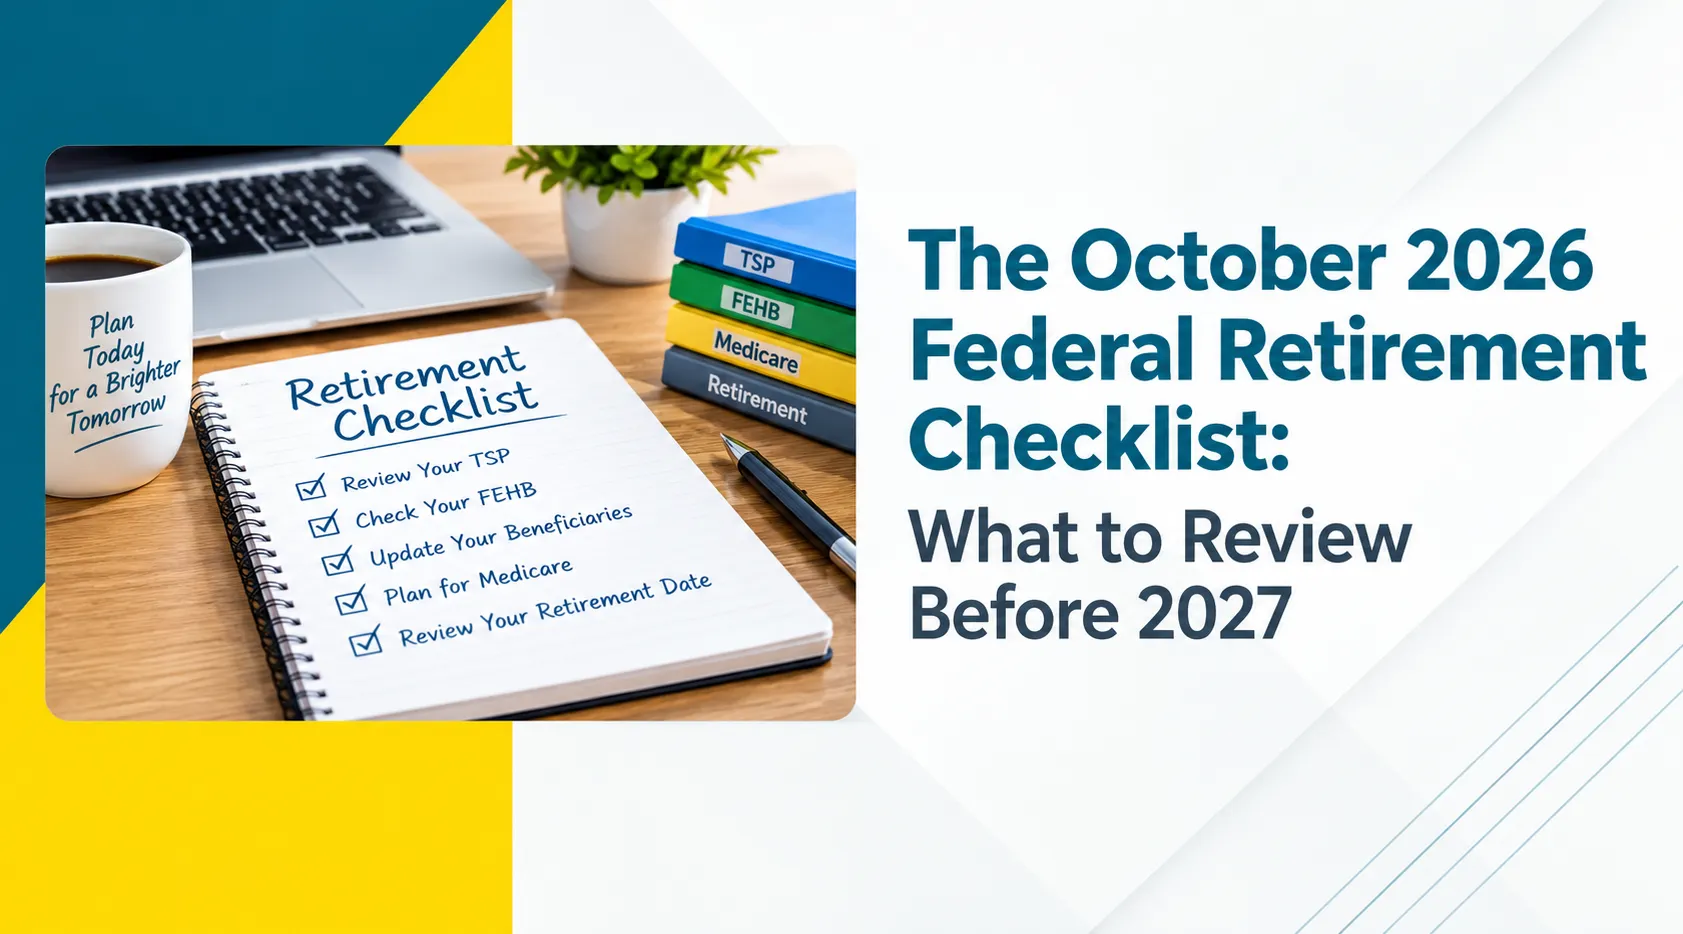
FEHB itself doesn't generate income. It provides group health insurance that continues into retirement, subject to deductibles, copayments, and plan limits. As you prepare for retirement, it's important to review your health coverage alongside other federal benefits, contribution decisions, and upcoming deadlines. Use this October 2026 federal retirement checklist to identify important items to review before 2027.
Planning retirement income means sizing each pillar, timing when each one starts, and understanding how one choice (such as when to claim Social Security) changes the pressure on the others.
Your FERS Annuity: The Guaranteed Pension Pillar
According to OPM, the U.S. Office of Personnel Management, the standard FERS basic annuity formula is 1% of your High-3 average salary multiplied by your years of creditable service. If you retire at age 62 or older with at least 20 years of service, the multiplier rises to 1.1% for every year of service. That change gives you a permanent 10% lift on your lifetime annuity.
The High-3 average salary is OPM's term for the highest average basic pay over any three consecutive years of service, which usually falls at the end of your career. Basic pay generally includes locality pay but excludes overtime, bonuses, and most allowances, per OPM.
FERS employees generally become eligible to retire with an immediate, unreduced annuity at the Minimum Retirement Age, or MRA. The MRA is currently age 57 for those born in 1970 or later, per OPM. Once you meet the eligibility requirements, understanding the retirement application process and potential processing delays becomes an important next step. Read our latest update on the OPM retirement backlog falling below 10,000 claims to learn what the lower backlog means for federal retirement applications.
You can retire at the MRA with 30 years of service, at age 60 with 20 years, or at age 62 with 5 years. Retiring at the MRA with only 10 to 29 years (sometimes called MRA+10) triggers a 5% per year reduction for every year you are under age 62, according to OPM's FERS retirement guide.
OPM also lets MRA+10 retirees postpone the annuity start date to avoid the age reduction entirely. You can postpone to age 60 with at least 20 years of service, or to age 62 with 10 years.
A worked example: an employee with a $110,000 High-3 and 30 years of service who retires at age 62 receives $110,000 × 30 × 1.1% = $36,300 per year under OPM's published formula. The same employee retiring at age 60 with the same service would use the 1% multiplier, yielding $33,000. That's $3,300 per year less, for life.
FERS annuities receive a modified cost-of-living adjustment that federal planners often call the "diet COLA." Under 5 U.S.C. § 8462, when the annual COLA tops 3%, eligible FERS retirees receive the full figure minus 1 percentage point.
SSA announced the 2027 Social Security COLA at 3.6% on October 14, 2026. That announcement produces a final 2027 FERS COLA of 2.6%, alongside the full 3.6% that CSRS annuitants receive.
Not every FERS retiree receives a COLA. It generally applies to retirees age 62 and older, disability retirees, survivors, and certain special-provision retirees such as law enforcement officers and firefighters, per OPM. Some disability retirees are subject to specific exceptions. OPM prorates the January 2027 increase for annuities that began during 2026.
Your TSP in 2027: The Savings Pillar
The TSP, or Thrift Savings Plan, is the federal government's tax-advantaged retirement savings program. For many FERS employees, it's one of the main sources of retirement savings alongside the FERS annuity and Social Security.
For 2026, the last year with official IRS figures at the time of this writing, the elective deferral limit is $24,500, per IRS Notice 2025-67. Employees who turn 50 or older during the year may add an $8,000 catch-up contribution. If you're planning to retire in the following year, it's also important to consider how your contribution strategy fits into your retirement timeline. Read our guide on choosing the right retirement date in 2027 to understand how retirement timing can affect your benefits, income, and other financial decisions.
The expanded SECURE 2.0 catch-up for employees who turn 60, 61, 62 or 63 is $11,250 for 2026, according to the Federal Retirement Thrift Investment Board. The IRS has not yet published a confirmed 2027 figure for this higher catch-up.
The IRS hasn't officially published the 2027 TSP contribution limit either. Based on IRS inflation adjustment formulas, FedTools and other independent calculators project the 2027 elective deferral limit at approximately $25,500.
Treat this number as a projection until the IRS releases its official Notice, typically in early November. The TSP website at tsp.gov is the authoritative source and will update when the IRS makes the announcement.
FERS employees automatically receive an agency contribution to their TSP equal to 1% of basic pay. Agencies add a dollar-for-dollar match on the first 3% you contribute, plus a 50-cent-per-dollar match on the next 2%. That totals a 5% agency contribution when you contribute at least 5%, according to tsp.gov.
The TSP calculates matching each pay period. An employee who reaches the IRS elective deferral limit too early in the year misses agency matching contributions for the remaining pay periods.
The TSP calculator at tsp.gov helps federal employees spread contributions evenly to capture the match through the final pay period.
You can split contributions between traditional (pre-tax) and Roth (after-tax) accounts. The TSP invests savings across the G, F, C, S, and I individual funds or the age-based Lifecycle (L) funds.
A SECURE 2.0 rule change that applies in 2026 continues into 2027. Under final IRS regulations, catch-up-eligible participants whose prior-year wages from the plan sponsor exceed the IRS threshold ($150,000 for 2026, indexed for later years) must make their catch-up contributions as Roth contributions. The Federal Retirement Thrift Investment Board has signaled that the TSP will apply these provisions. Along with understanding contribution rules, federal employees should also monitor how their retirement investments are performing. Review the latest TSP fund performance for September 2026 to stay informed about TSP fund returns.
Social Security in 2027: What Federal Retirees Can Expect
Social Security is a core income pillar for FERS employees, who pay into the system through FICA taxes just like private-sector workers. According to the SSA, or Social Security Administration, Social Security retirement benefits will rise by a 3.6% cost-of-living adjustment in January 2027.
The SSA announced the figure on October 14, 2026, and estimates it will raise the average retired worker's monthly benefit by about $75.
The Social Security taxable maximum, the top earnings amount subject to Social Security tax, is scheduled to rise to $192,300 in 2027 from $184,500 in 2026, per the SSA's October 14, 2026 announcement. Federal employees above that threshold don't pay the 6.2% OASDI tax on earnings beyond the cap, but those earnings also don't count toward their benefit calculation.
Most CSRS employees, by contrast, didn't pay into Social Security through their federal service. They therefore don't earn Social Security credits for those years.
CSRS Offset employees are an exception. They are generally former CSRS employees who returned to federal service after a break of more than one year, had at least five years of CSRS-creditable service, and are covered by both CSRS and Social Security. They remain under CSRS Offset rules unless they elect FERS or otherwise move to it. Understanding how retirement benefits are adjusted over time is also important, particularly when reviewing 2027 FERS COLA changes and their potential impact on retirement income.
CSRS Offset employees pay FICA taxes, and their CSRS annuity drops (offsets) when they become eligible for Social Security.
For CSRS and CSRS Offset retirees who also qualified for Social Security through other work, the Social Security Fairness Act, signed into law in January 2025, repealed the Windfall Elimination Provision and the Government Pension Offset. SSA has been issuing adjusted benefits since early 2025.
The FERS annuity supplement, also called the Special Retirement Supplement or SRS, approximates the Social Security benefit you earned during federal service. OPM pays it monthly from the retirement date until the retiree turns 62.
Not every FERS retiree qualifies. The supplement generally applies to employees who leave with an immediate, unreduced annuity under the MRA+30 or age 60+20 rules, and to certain special-category and involuntary retirees under separate OPM rules.
MRA+10, deferred, and disability retirees don't qualify. The supplement is subject to the Social Security earnings test and ends automatically at age 62 whether or not the retiree actually files for Social Security.
FEHB in 2027: Keeping Health Coverage into Retirement
FEHB, the Federal Employees Health Benefits Program, is an important health benefit that eligible federal employees may continue into retirement. The government preserves its premium contribution under the same formula it uses for active employees.
According to OPM's September 30, 2026 announcement for the 2027 plan year, the average enrollee share of FEHB premiums will rise 10.9% in 2027. Total premiums will rise 9.3% overall. OPM has described this as the third consecutive year of double-digit enrollee premium increases.
To carry FEHB into retirement, you generally must be enrolled in FEHB (or covered as a family member) for the 5 years immediately before retirement. You must also be eligible for an immediate annuity. Because these requirements can affect your retirement healthcare coverage, reviewing your eligibility and other federal benefits before leaving service is important. Explore our federal retirement planning services to learn more about the available planning support.
An exception applies if you've been enrolled or covered for the full period since your first opportunity to enroll, even if that period is less than five years. OPM calls the main requirement the five-year rule.
This is a critical eligibility requirement in the federal benefits package. Review your coverage carefully before changing or dropping FEHB during your final working years.
In retirement, the government continues its FEHB premium contribution under the same formula it uses for active employees, per OPM. Under that formula, the government pays the lesser of 72% of the program-wide weighted average premium or 75% of the enrollee's selected plan premium. The exact dollar contribution depends on which plan and tier the annuitant chooses.
The remainder is the enrollee share, which OPM deducts from the monthly annuity payment.
Open Season for the 2027 plan year runs from November 9 through December 14, 2026, according to OPM. Any FEHB-eligible federal employee or annuitant can change plans or switch between Self Only, Self Plus One, and Self and Family enrollment tiers.
FEHB and the Postal Service Health Benefits Program (PSHB) have separate eligibility rules. Most Postal Service employees and annuitants generally must enroll in PSHB rather than FEHB. Postal Service employees and annuitants may continue coverage under a non-Postal family member's FEHB plan where that applies, per OPM.
Specific eligibility provisions, rather than open enrollment, govern movement between FEHB and PSHB.
FEDVIP, the Federal Employees Dental and Vision Insurance Program, uses the same Open Season window.
Federal Pension Advisors recommends reviewing each year's rate chart against your current plan before Open Season closes.
Comparison Table: The Four Pillars of Federal Retirement Income in 2027
The table below summarizes each retirement income pillar as it stands for the 2027 plan year, with the primary source for every figure.
The FEHB enrollee share increase of 10.9% is roughly three times the Social Security COLA and more than four times the FERS COLA. These aren't directly comparable (one is a health-insurance cost increase and the others are benefit increases), and individual FEHB plan increases vary.
Even so, health premiums are likely to consume a growing share of fixed retirement income for many federal retirees in 2027. This is a key planning concern if you're finalizing your 2027 retirement decisions. Reviewing your estimated take-home pay can help you understand how benefit deductions and other expenses may affect your retirement budget. Use the Federal Employee Paycheck Calculator to estimate your paycheck and better understand your income.
How the Four Pillars Work Together: A 2027 Retirement Income Example
Consider a FERS employee retiring on January 1, 2027 at age 62 with 30 years of creditable service and a $120,000 High-3 average salary. The figures below are illustrative, meant to show how the pillars combine.
Verify your actual benefits using OPM's retirement calculator and the SSA's my Social Security account.
FERS annuity: Using OPM's formula, $120,000 × 30 × 1.1% equals a gross annual FERS annuity of $39,600, or $3,300 per month before survivor benefit reductions and taxes.
TSP: An employee who saved consistently and holds $500,000 in the TSP at retirement could withdraw roughly $20,000 in the first year under a 4% initial-withdrawal convention. This isn't an OPM or TSP figure. It's a commonly cited planning rule of thumb, and the actual sustainable rate depends on fund allocation, market returns, and sequence of withdrawals.
Social Security: At age 62, this retiree can begin Social Security at a permanent reduction compared to the full retirement age of 67, according to SSA. If the SSA estimate at age 62 is $2,100 per month, the first-year Social Security income is $25,200. Waiting until full retirement age or age 70 would increase that monthly figure meaningfully.
FEHB: Assume Self Plus One in the Blue Cross and Blue Shield Service Benefit Plan Standard Option (enrollment code 106). Per OPM's 2027 FEHB rate charts published September 30, 2026, the enrollee share is $449.89 biweekly for non-postal employees. When evaluating retirement expenses, federal employees should also consider how their expected retirement income fits into their overall budget. Use the FERS Supplement Calculator to estimate potential FERS Special Retirement Supplement income if eligible.
That converts to approximately $974.76 per month for annuitants, or about $11,697 per year. The government pays its share directly to the carrier.
Illustrative gross retirement income from the three income pillars: $39,600 + $20,000 + $25,200 = $84,800. Subtracting the $11,697 Blue Cross Standard Option premium leaves approximately $73,103.
This is illustrative pre-tax cash flow, not take-home income. These figures don't reflect federal and state income taxes, any survivor benefit election, FEGLI premiums, FEDVIP premiums, and Medicare Part B at age 65. Individual numbers will vary based on earnings history, plan choices, and tax situation.
2027 Changes Federal Retirees Should Watch
Several confirmed and proposed 2027 changes bear on federal retirement income planning this year:
- The President's 2027 alternative pay plan calls for a freeze of base and locality pay for most civilian federal employees, with targeted exceptions for law enforcement, per Federal News Network.
- A pay freeze in your final working year may limit High-3 growth for employees who would otherwise have received a general pay adjustment.
- The 2027 FERS diet COLA is 2.6%, compared with 3.6% for CSRS and 3.6% for Social Security.
- Those figures reflect the SSA announcement of October 14, 2026 and OPM's statutory FERS COLA formula under 5 U.S.C. § 8462.
- Average FEHB enrollee premiums are rising 10.9%, per OPM, the third straight year of double-digit increases.
- The projected 2027 TSP elective deferral limit is $25,500, with official IRS confirmation expected in early November 2026.
- The mandatory Roth catch-up rule under SECURE 2.0 took effect January 1, 2026 for catch-up-eligible TSP participants whose prior-year wages from the plan sponsor exceeded the IRS threshold, and continues to apply in 2027.
Conclusion
Federal retirement income in 2027 rests on four coordinated pillars: the FERS basic annuity, the TSP, Social Security, and FEHB. Each one is moving independently next year. Understanding how these benefits work together can help you prepare for retirement and evaluate your income needs. Schedule a free federal retirement consultation to discuss your retirement timeline, benefits, and income planning considerations with an independent, licensed financial professional.
The 2027 FERS diet COLA is 2.6% against Social Security's full 3.6% increase. FEHB enrollee premiums are rising 10.9% on average, and the IRS will confirm the 2027 TSP elective deferral limit in early November.
Coordinating all four pillars (timing, elections, and tax treatment) is the work of a retirement income plan. Federal Pension Advisors, a retirement planning firm specializing in federal employee benefits, can review your specific numbers before Open Season closes on December 14, 2026. You can also use these federal retirement planning checklists to organize important retirement tasks, review your benefits, and prepare for key decisions.
Frequently Asked Questions
When can I retire with full benefits under FERS?
FERS employees retire with an immediate, unreduced annuity at the Minimum Retirement Age (MRA) with 30 years of service, at age 60 with 20 years, or at age 62 with 5 years, per OPM. MRA+10 retirees face a 5% per year age reduction. They can avoid it by postponing the annuity start to age 60 (with 20 years) or age 62.
How is my FERS pension calculated?
Under OPM's standard formula, your FERS basic annuity equals your High-3 average salary multiplied by your years of creditable service multiplied by 1%. The multiplier rises to 1.1% if you retire at age 62 or older with at least 20 years of service. That change produces a permanent 10% increase in your lifetime annuity.
What happens to my FEHB coverage when I retire?
If you meet OPM's five-year enrollment rule (or the first-opportunity-to-enroll exception) and retire on an immediate annuity, you can generally continue FEHB coverage into retirement. The government keeps contributing under the same FEHB formula it uses for active employees.
That's the lesser of 72% of the program-wide weighted average premium or 75% of your plan premium. Your share depends on the plan, tier, and annual rates.
Can I collect FERS and Social Security at the same time?
Yes. FERS employees pay into Social Security during federal service and may collect both their FERS annuity and Social Security retirement benefits simultaneously once eligible. Social Security benefits can begin as early as age 62 at a reduced amount, with full retirement age at 67 for those born in 1960 or later, per SSA.
What is the FERS supplement and who qualifies?
The FERS annuity supplement, or Special Retirement Supplement (SRS), approximates the Social Security benefit you earned during federal service, per OPM. It generally applies to retirees who leave under MRA+30 or age 60+20, plus certain special-category and involuntary retirees.
MRA+10, deferred, and disability retirees don't qualify. It ends at age 62.
How much should I contribute to my TSP in 2027?
To capture the full agency match, FERS employees should contribute at least 5% of basic pay every pay period, which triggers a 5% agency contribution, per tsp.gov. Because the TSP calculates matching per pay period, spread contributions evenly across the year to avoid missing matches. The 2027 projected elective deferral limit is $25,500.
Disclaimer:
This article is for educational and informational purposes only. It is not financial, tax, or legal advice, and it does not represent an official statement from the U.S. Office of Personnel Management (OPM), the Social Security Administration (SSA), the Internal Revenue Service (IRS), or any other government agency. Retirement benefits, contribution limits, premiums, and eligibility rules may change. Projected figures are estimates and should not be treated as confirmed amounts. Verify current information with the appropriate government agencies and consult a qualified financial, tax, or legal professional before making retirement decisions.
Thomas A. Doherty
Thomas A. Doherty is a retirement planning consultant with 35 years of experience helping individuals, federal employees, academic employees, and business owners better understand their retirement options. His work focuses on helping clients make the most of their available benefits, insurance policies, and investment plans so they can build more stable retirement income and reduce unnecessary financial risk.